Britain, Business, China, Economic, European Union, Government, International trade, Politics, Society

A ruthless new Chinese plan that is grinding the West down

CHINA

Intro: China is single-mindedly building enough industrial might to supply the world with just about every major manufacturing product it needs

The most important economic story of our time, by far, is seriously under-covered by both the media and our political class which has largely been ignored. Preferring to obsess, debate, and divide over mere fripperies while a clear and present danger gathers momentum to our economy, our prosperity, and our very way of life.

The scale of the threat is now unmistakeable: China is single-mindedly building enough industrial might to supply the world with just about every major manufacturing product it needs.

Beijing has more capacity than it needs to meet the demands of its domestic markets. Yet it is still adding more at a rapid rate – all of it geared to exports.

It is the clear policy of President Xi Jinping to make the rest of the world dependent on Chinese exports, destroying much of Western business in the process.

It is no less than a bid for global economic domination, with all the global political power that would follow – without the necessity of a shot being fired.

And, so far, partly thanks to the entrenched myopia of feckless politicians on both sides of the Atlantic, it’s proceeding apace without hindrance.

What’s new? you might say. Isn’t it apparent that we have already lived through what we now call China Shock 1.0, an era which started about 25 years ago when Beijing was granted access to global markets?

The world was quickly flooded with cheap Chinese products that not only drove down prices but also drove many Western companies out of business and workers out of jobs.

Well, yes reader, we have and, despite all the pain and disruption it caused, there was never much pushback from the West. True, there were losers, from America’s mid-West to the textile towns of northern England, where blue-collar communities suffered.

But undoubtedly there were more winners from the lower prices and our political masters on both sides of the Atlantic thought what China was exporting – clothes, toys, furniture, household appliances – were not the sort of goods advanced economies in the 21st century should be involved in making anyway. So we just grew to live with it. China Shock 1.0 became the status quo.

It’s now being superseded by China Shock 2.0, an even bigger disruption and far more of a threat because it targets the advanced industries in which the West thought its future lay.

TWO

We’re talking the sort of sophisticated, high-end manufacturing of goods such as precision machine tools, robotic arms for assembly lines, electric vehicles (EVs), the new breed of batteries they require and a new generation of pharmaceuticals.

China is long past the stage of contenting itself by creating the capacity to supply its own needs for these products. It’s building enough to supply the world. A pipe dream? Far from it – it’s already happening.

China can already build enough EVs to supply the entire European market. That’s ten million cars a year. It will soon have enough capacity to meet the global demand for EVs – and the batteries that make up so much of their value.

Indeed, such is the size of Chinese capacity in EVs and their batteries, not to mention their competitive edge, there is really no scope for anybody else to enter the market at scale. We are approaching an age in which the vast majority of EVs and nearly all the key components in them will be Chinese.

That’s already true of solar panels. Fifteen years ago, Europe – especially Germany – had a thriving solar panel industry. Then China entered the fray. There is now no European solar panel industry worth talking about. Wind turbines will be next.

Perhaps most concerning of all, China is building up an unbeatable lead in the market for precision machine tools and advanced industrial robotics. That’s what makes the threat of China Shock 2.0 so much more existential than China Shock 1.0. We’re no longer talking about cheap clothes for teenagers or toys for children. We’re talking about the industries of tomorrow.

To understand more clearly what’s happening, let’s go, briefly, to two places.

First, Dongyuan in Guangdong Province, just north of Hong Kong. This town used to be full of factories churning out cheap toys, shoes, clothes, and appliances for Western markets. No longer.

Now it’s a “factory for factories” making high-value capital goods for global industry from machine tools to robotic arms and microchips – exactly the sort of advanced manufacturing Germany and Japan used to dominate.

Now let’s go to Dresden in Germany, home to Volkswagen’s showcase plant known as the Transparent Factory, so called because it was designed with glass walls to let the public watch workers and machines assemble VW’s world-beating cars.

Except there’s no point going there – because car production ceased last December. Reeling from China Shock 2.0, VW is now slashing tens of thousands of jobs in Germany, closing plants and, to cap it all, is opening an export hub in China from which to supply global markets. Just days ago, VW announced that 50,000 workers will lose their jobs. The company’s share price reacted favourably.

The plight of VW is the plight of German industry. Last year, Germany lost 150,000 skilled, well-paid industrial jobs. This year, it’s still losing them at a rate of 10,000 a month.

THREE

Politicians in Baden-Wurttemberg, Germany’s hitherto prosperous manufacturing heartland, now speak openly of it becoming the “Detroit of Europe”. This is a reference to the US city nicknamed “Motown” thanks to its domination of car manufacturing, which saw its population decline from close to two million in the 1950s to just over 600,000 in 2020 as the car giants moved out.

That prospect tells us something else about China Shock 2.0. Whereas the first shock took more of a toll in America, where there was more low-end manufacturing than in Europe, it is advanced manufacturing in Europe that will bear the brunt of the second Chinese wave.

We can date the start of China Shock 2.0 to 2021 when, in the wake of the world’s biggest ever property crash, President Xi decided it was time to move resources out of property and into advanced manufacturing. That was only five years ago. And yet there’s already been an explosion of Chinese exports to Europe.

The European Union runs a trade deficit with China of one billion euros per day. It’s heading for an annual deficit of half a trillion euros next year – twice the pre-Covid deficit. And, even though we’re only in the early days of the shock, it’s already exacting a grim economic toll.

Bankruptcies and insolvencies in the EU are at a ten-year high. European growth is sluggish. Industrial production is actually declining. Germany now imports more sophisticated capital goods from China than it exports to China – Shock 2.0 in action.

America erected trade barriers to China Shock 2.0, including a 100 per cent tariff on Chinese EVs. Other Chinese products face tariffs of around 25 per cent, far higher than European tariffs where, par for the course, the EU has dithered in its response to China. It’s still dithering, making Europe a much softer target.

It’s not as if the EU hasn’t been warned. France’s official planning agency starkly reported earlier this year that, without action, Europe was heading for “industrial devastation”.

Entire chunks of European industry – cars, machine tools, wind turbines – would go the way of European solar panels. “Rapid industrial wipeout in under a decade” beckoned, with 55 per cent of European manufacturing at risk (60 per cent in Germany).

But what of the UK? The good news (in relative terms) is that because we don’t have that much advanced manufacturing we are less exposed than the EU in general and Germany in particular.

The bad news is that we’re governed by politicians who have no idea there is any kind of threat or, if they do, simply ignore it.

In fact, it’s worse than that. Far from even modestly protecting our interests, we’ve reduced tariffs on imports from China to facilitate the Government’s bizarre dash for Net Zero.

As energy secretary, Ed Miliband actually embraced China Shock 2.0 to further his own green goals. We stuck with a standard 10 per cent tariff on cheap Chinese EVs because he wanted people to buy them.

And, not content with making it easy for Chinese EVs, the Government decided to penalise our own carmakers for not selling enough EVs.

In July, British vehicle output was a mere 64,000 units, down 12 per cent on the year. A decade ago we produced 1.5 million vehicles a year.

This year it is expected we won’t produce even half of that. In 2025, we managed under 720,000, down 8 per cent on the year before. Thanks to China Shock 2.0 and our own Government’s folly, we probably will not have a car industry at all in ten years’ time.

As for so-called “green jobs”, we already have precious few of them. Thanks to the Net Zero obsession, our green supply chains for all manner of things – batteries, cathodes, anodes, solar/wind turbine components, critical minerals – are already China-dominated.

Had we taken our time, we could have fostered more domestic suppliers. Instead, the Government decided to embrace cheap Chinese green tech to meet its artificial climate targets, which have taken precedence over everything else.

There is no coming back from this. We have favoured China and sacrificed any hope of a new industrial base, while jeopardising our security. So much for industrial policy, despite rampant talk of it in Labour circles. Not so in China, where industrial policy is paramount. The scale of the commitment is breathtaking – even frightening. There was a time when Chinese industrial policy was confined to backing a few favoured sectors.

No longer. The whole might of Chinese Communism – state-owned banks, state-owned companies, local government – has been mobilised in pursuit of what’s being called “the industrial policy of everything”. China’s economic growth, which secures the continued dominance of the Communist Party, is increasingly dependent on exports.

China’s currency, the yuan, is manipulated down against other currencies to make these exports even more competitive – and to make goods that China imports more expensive.

There you have another key feature of China’s second shock: it isn’t just the biggest export drive the world has ever seen, it’s a strategy to reduce China’s dependence on imports. Investment has been showered on those parts of advanced manufacturing which Beijing perceives to be over-dependent on imports.

Replace imports with homegrown production, keep the currency cheap to favour exports and, voila, you have a modern mercantilism – an ancient economic doctrine which promotes exports above all else and which fell out of favour years ago.

President Xi has revived it and combined it with autarky, a policy of national self-sufficiency. Those who think we can live with China Shock 2.0 because China’s massive domestic market will still be open to our exporters really have no idea what they’re talking about.

First, it was never open in the first place. Second, the shutters are coming down. Third, President Xi thinks autarky works.

FOUR

China now runs a traded goods surplus of $1.2 trillion (£900 million) with the rest of the world, with bigger surpluses to come. Xi isn’t doing this just because he can. He’s doing it because with economic dominance comes global political power.

When you dominate global trade the way China envisages, you dominate global supply chains. Just as America has projected its power and influence through its effective control of the global financial system so China aims to do the same through its control of global supply chains.

It’s already flexed its muscles. Japan learned how vulnerable it was to Chinese supply chains when it recently had the temerity to stand up for Taiwan.

The EU fears retaliation if it takes a tough line against China. Even America has backed off confronting China on trade. Say hello to the shape of things to come.

We are in no position to deal with it. The EU is rudderless. America is run by a President who prefers to pick fights with allies rather than build the united front needed to confront China Shock 2.0. Our own political leadership could not be less equipped to rise to the challenge.

By the time they grasp the implications of 2.0, we’ll be on to China Shock 3.0. It’s already stacking up. This won’t involve Chinese exports of EVs or robotic arms. Not a single container ship will be involved.

It will be the export of the operating system itself. Chinese-built AI models embedded in the software running Western factories, Chinese-standard batteries and chips wired into the next generation of Western infrastructure and EVs. Chinese firms setting the technical rules the rest of us will have to follow because, by then, there will be no alternative supplier left standing.

Beijing will own the plumbing of the modern global economy. Domestic politicians in the West will be left talking about issues that have little or no significance.
Standard
Arts, Books, China, Communism, Education, History, Society

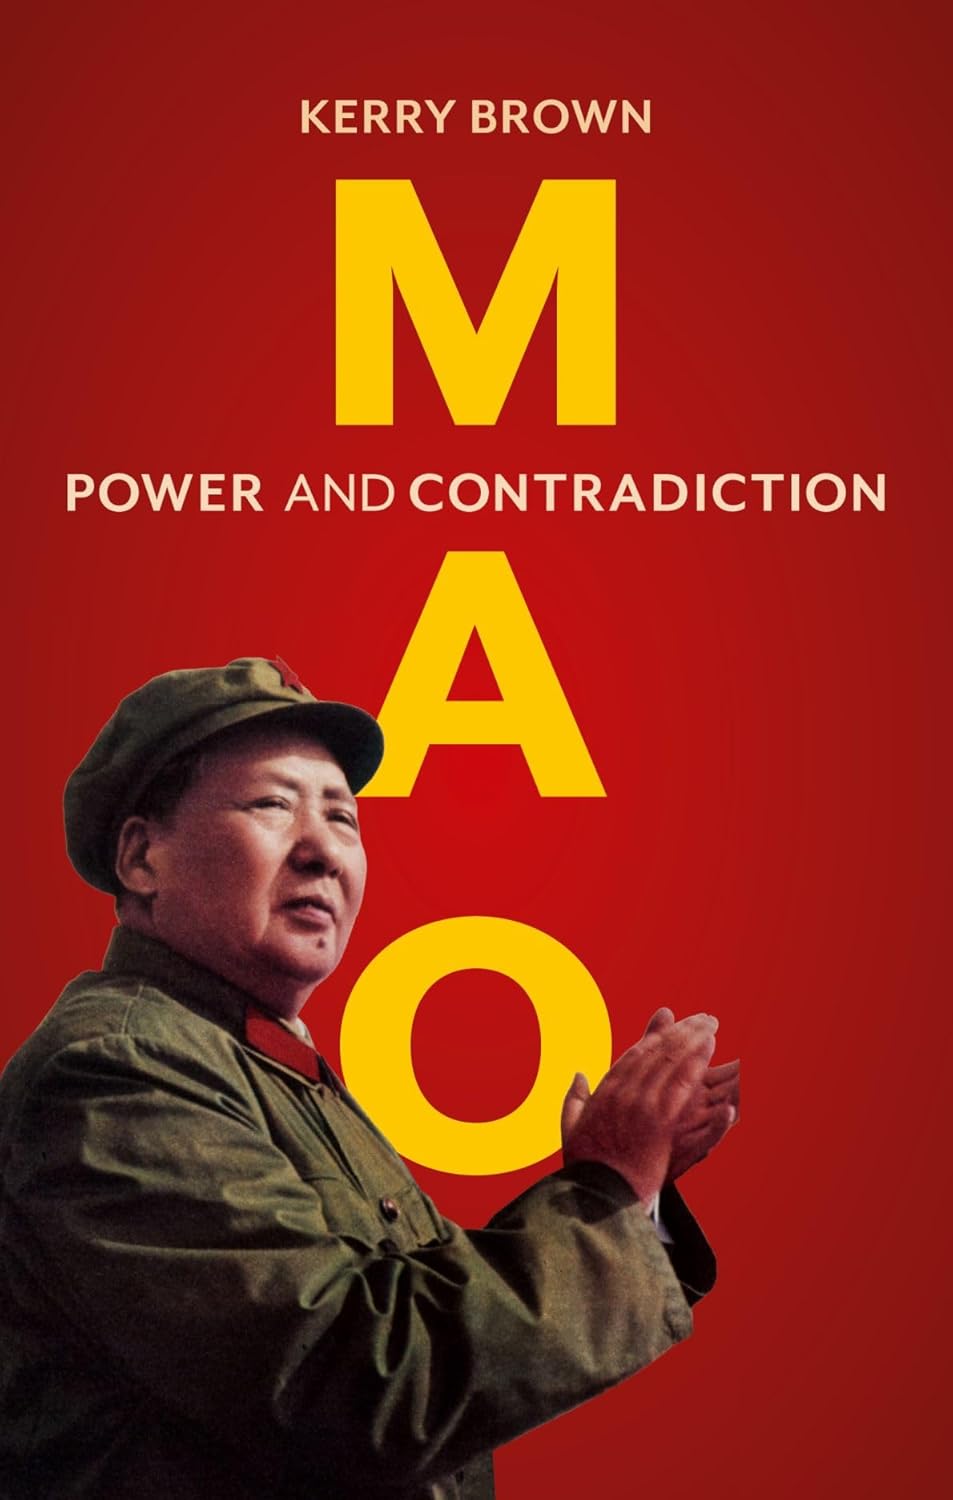
Book Review: Mao

LITERARY REVIEW

Intro: The central argument of Brown’s thesis is that Mao was a ‘moderniser through destruction’. He believed that for a new China to be born, the old one had to be violently uprooted. The book suggests that while Mao’s methods were often catastrophic, the unified, assertive China we see today is an inescapable result of his reign

Kerry Brown writes that “Mao’s provocations… would have suited the world of social media and Twitter/X”. That’s a fertile observation. One could well imagine an @Mao account, or a podcast – The Chairman Mao Experience – attracting a huge and hungry following.

Mao Zedong was, after all, a famed dispenser of earthy aphorisms. He told an astonished hall in 1959: “Comrades… if you have to s—, s—! If you have to fart, fart! You will feel much better for it.” He was obsessed not so much with state-building as with the more intimate endeavour of moulding minds. “Simple slogans, cartoons, and speeches”, he wrote, “have produced… a widespread and speedy effect among the peasants.” Social media would have been a central platform for his rhetoric.

Even in death, Mao trips us up. In the half a century since his passing in 1976, biographers and historians of China have failed to reach consensus on what drove him, what degree of responsibility he bears for the tragedies of the early People’s Republic, and what his contributions were to the wealthy and successful China of 2026. He ran the country for 27 years, yet remained an enigma – associated, at various times in his life, with violence and mercy, Confucianism, and techno-utopianism. In his new biography Mao, Brown, professor of Chinese studies at King’s College, London, all but emits a sigh, surveying the task ahead: “Getting a clear sight of who Mao was… presents a massive challenge.”

Some early signs provide pointers. Young Mao, born in imperial China in 1893, was fiercely opposed to the ruling “Simple slogans, cartoons, and speeches”; yet, he was schooled in the Confucian classics, and was impressed by the importance of self-cultivation. It was a short hop from self-cultivation to the cultivation of others’ selves – in particular those of the vast mass of China’s peasantry, whose loyalty and labour were required for revolution.

Mao came to believe that Marxism offered the best blueprint for achieving this. Russia’s Bolsheviks had shown that what Brown calls “an enlightened vanguard of activists” armed with a simple critique of present injustices could rally the masses to their cause. The people of Hunan province, where Mao built his early political base, possessed, in his estimation, “no brains, no ideals, and no basic plan”. Changing that required, in Brown’s words, “the framing of social relations in elemental terms as a struggle between… two great forces”. One only had to exchange Marxism’s “capitalists” with “landlords” for China’s peasants to raise their gaze beyond their own fields and throw themselves into collective action. Mao deployed night-schools and propaganda to this end, providing just enough education to create a biddable mass that would “rise like a mighty storm, like a hurricane, a force so swift and violent that no power… [would] be able to hold it back”.

Compromise was not in Mao’s DNA. In 1921, while still a marginal figure in the party, he attended the fabled first meeting of the Chinese Communist Party in Shanghai. The location, then in the city’s French concession, is today regarded in China as sacred ground, festooned (the author tells us) with TV screens and interactive guides. And yet: so disillusioned was Mao by the CCP’s pragmatic decision to forge a temporary alliance with the Chinese Nationalists that he boycotted its second congress in 1922. (In later years, he would pretend he’d done no such thing, and only failed to locate the address where the meeting was being held.)

Mao once declared that revolution is “not a dinner party, or writing an essay, or painting a picture, or doing embroidery . . . a revolution is an insurrection, an act of violence where one class overthrows another”. Brown takes the reader on the wild ride that was Mao’s life in the 1930s and 1940s: his quick return to the fold, the rise of the CCP, its fight against Japanese invaders, then all-out civil war with Chiang Kai-shek’s Nationalists – whom Mao had driven out of China and into Taiwan by the end of 1949, thus establishing Communist rule.

Then comes the perplexing mix of success and tragic failure that were the early years of the People’s Republic of China. Greatest of all disasters was the Great Leap Forward of 1958–62, during which a staggering 50 million people may have died (reliable statistics are impossible to come by). How to explain the gargantuan folly of setting up backyard steel furnaces in villages across the country, producing shoddy tools and utensils, while people were left eating tree bark and raw wheat?

Prof. Brown points us towards “Mao Zedong Thought”, the “philosophy” that seems to have turned on a terrifying sense of China’s population as an expendable means towards utopian ends. Those village furnaces might have claimed untold lives – consuming farmers’ tools and time when they should have been tending their fields – but for Mao they were a symbol of Chinese modernity. A nuclear exchange would be regrettable, but China had so many people that no enemy could possibly kill them all. Food aid was offered to China’s neighbours during the height of the famine, because you can’t put a price on projecting an air of progress. Brown wonders whether Mao understood economics at all – whether “capitalism” was, to him, little more than “a term of abuse or criticism for those he regarded as… enemies, rather than something [of which] he had a clear understanding”.

Brown is like a trustworthy tour guide, knowledgeable and clear, but not always sure which sights we most need to see. Digressions into the lives and thinking of other figures occasionally takes up space that might have been better used in rounding out our sense of the chairman himself. Writing about a figure like Mao isn’t easy; but readers may still find themselves hankering after a more vivid personal portrait, alongside answers to some of the questions thrown up by Mao and Maoism.

For instance, important aspects of Mao’s private life are passed over rather quickly. He was often consumed by what might now be described as anxiety and low mood, over fears of his rivals plotting and scheming against him. He withdrew from public life for long periods at a time before returning with fresh and deadly energy – most famously at the time of The Cultural Revolution of 1966-76. And while we must be wary of sensationalism, it seems clear that Mao had a fondness for young women, especially during his later life. All these things might be mined for insights about one of the pivotal figures of the 20th century.

Similarly, we read about the extraordinary violence of the Cultural Revolution without being helped to understand what could make people do such things. So-called “sent-down-youth” from urban China were forced out into the countryside “to seek lived experiences of the revolution”. The results extended to forced marriage, rape, and even murder at the hands of rural Chinese who were fearful that their food and resources were under threat. Mao was the prime instigator and orchestrator of this infamous episode in Chinese history, alluding at the outset to the utopian potential of “disorder” under heaven.

Were Mao’s pathologies poisoning a nation, or coaxing to the surface its darkest inclinations? Brown is surely correct when he says that “it is hard to work out the psychology of a man who was almost constantly calculating and balancing different forces around him”. Still, a tighter curating of key moments and insights plus some judicious speculation might have helped the analysis in this book be more cohesive and compelling. As it is – and in fairness, perhaps this is true to the nature of the chairman – Mao Zedong risks once again slipping through our fingers.

– Mao by Kerry Brown is published by Reaktion, 272pp

Standard
China, Digital Economy, Economic, International trade, United States

Essay: Hormuz has exposed flaws in Beijing’s economic model

CHINA’S ECONOMIC MODEL

Intro: As the US president prepares to visit Beijing, he may have ended China’s decades-long growth miracle. Trump’s war on Iran, and especially the closure of the Strait of Hormuz, has China in a chokehold

In the modern era, we have witnessed among many things, a robot that can win a half-marathon, a pilot-less plane, a soap opera made by AI, and an electric supercar with a top speed of 308 miles per hour.

Whenever a new bit of Chinese-made tech goes viral online, it seems to be something that goes further, faster, or smarter than ever before. And every time, it feels like a silicon-made metaphor for China’s coming of age as a global superpower.

As Donald Trump prepares to visit Beijing this month, he confronts a Communist Party regime that, on the face of it, looks on the up. Beijing controls access to critical minerals used by his military, and holds at least $700bn (£517bn) in outstanding loans to his government.

Little wonder that, even as he pours scorn on Sir Keir Starmer, Emmanuel Macron, Friedrich Merz and Mark Carney, Trump deferentially refers to his Chinese counterpart Xi Jinping as “the Highly Respected President of China”.

However, that doesn’t mean Trump is making things easy for Xi.

First he choked off the half-million daily barrels of oil that China was buying from Venezuela.

Now, his attacks on Iran, leading to the closure of the Strait of Hormuz, has squeezed another 40pc of Chinese crude supply.

An oil crunch is never good news, but Beijing was prepared for this. Through price caps, export bans, fuel stockpiles and home-grown alternatives to imported oil and gas, China has managed to stave off the early economic threat from the Iran War.

If the conflict drags on and the Strait of Hormuz remains closed, however, China could start to feel the pinch.  

A global slowdown or recession could cut demand for its exports, which have been almost single-handedly propping up the Chinese economy ever since the country’s great property crash of 2021.

And if that happens, Xi may struggle to keep a lid on three ticking time bombs sitting beneath China’s economy: its reliance on bloated factories churning out exports; its spiralling budget debts; and its alarmingly shrinking population.

Xi hopes to diffuse these problems by winning the global race on artificial intelligence, quantum computing, and robotics. But the Communist Party is also eager to stay in control, so it may struggle to make the most of this disruptive juggernaut.

The war against Iran isn’t going to plan for Trump. Yet whatever his intentions were, he may have triggered the tripwire that will blow up China’s decades-long growth miracle.

And this won’t be the only consequence of the Iran conflict that Xi is currently weighing up.

As ever, his thoughts will have quickly turned to Taiwan – an island whose reunification, he has previously said, is a task for his generation to fulfil.

He might like what he sees. The war in the Gulf may divert America’s attention, money, and resources away from the Pacific. It may strain alliances in which Taiwan has put faith.

If Iran’s asymmetric resistance to superior US forces is a play-book for Taipei, then Beijing can pick up strategies and tactics on how to push past it.

Chatham House, a think tank, says that a world in which the Trump administration is expressing a lot of transactionalism, and with the US maybe diminished by its failure in Iran, all of this opens up possibilities for Beijing vis-à-vis Taiwan.

Perhaps this is why Xi has been relatively quiet on Iran. Since the war began on February 28 he has only once picked up the megaphone, urging a swift reopening of Hormuz. This is likely to remain his top priority – the Chinese economy, and his regime’s legitimacy, may yet depend on it.

Economic shock

On Zhihu, a Reddit-style Chinese social media site, users enjoying a cloak of anonymity are swapping stories on the impact of the US-Iran war.

One user wrote: “My industry uses plastic as a raw material… Since plastic is a derivative of oil, the cost of raw materials has doubled and changes three times a day, with no stable price. As a result, global customers have stopped placing orders because they dare not order.

“Work has stalled, and the long-term high-pressure work is exhausting. I can’t change natural disasters or man-made calamities. Fine, I’ll go relax for a few days. But I realised that air ticket prices have also gone absurdly high, so I can’t go out.

“I have no choice but to squat every day in front of the Longjiang Braised Pork Leg Rice stall downstairs, asking, ‘Is it half price after 8pm?’”

China is powerfully exposed to the current of high costs rippling out from the closure of the Strait of Hormuz, the vital conduit for oil, gas, petroleum products, and fertiliser. China imports about 70pc of the oil it needs, of which about half comes from the Persian Gulf. Its shipments from there slumped by a third in March from a year earlier, and that number doesn’t even include the illicit Iranian oil.

On the gas front, about half of China’s gas imports come via pipelines from Russia, Myanmar and central Asia, with the rest arriving on LNG tankers. A third of that LNG comes via Hormuz, and imports plunged by 41pc in March.

For now, the damage may be less than these numbers might suggest, because China has spent the past decade building a huge and still growing domestic gas industry.

This insurance policy means home-grown output now satisfies almost two-thirds of China’s gas demand, so the Iran War has disrupted just 5pc of China’s total supply. It looks as if, in some ways, China has been preparing for this type of situation better than anybody else.

The Chinese have been similarly savvy with crude oil. Last year it bought 11.6 million barrels per day (bpd), taking advantage of lower prices to stockpile almost half a million bpd. By the end of 2025, that reserve totalled almost 1.4 billion barrels, vastly more than the rest of the rich world put together.

If China released supplies from this trove of black gold at a rate of 2 million bpd, a level that would largely negate the Hormuz closure, the stockpile would still last until at least the end of next year.

Still, the Chinese aren’t leaving anything to chance. Beijing told its refineries to stop exporting petrol, diesel, and jet fuel – in case supplies run low. But this has rebounded on Beijing. The move irked trading partners such as Vietnam, the Philippines, Singapore and Australia, whose fuel shortfalls have been exacerbated by China’s parsimony.

China appears to have now acknowledged that its stockpiles are almost too big, and that it needs to mend some fences. According to Bloomberg, exporters have now had approval to ship 500,000 tons to regular customers.

China’s biggest vulnerability to Iran, lies in its reliance on oil-based products like naphtha, which is vital to greasing the mighty Chinese industrial machine.

If you go back far enough in the chemical processing chain, or petroleum products, that’s where you’ll see the prices rise. Access to that is a continual problem, and that’s where the greatest fear is.

Producer price inflation, which was at or below zero last year, hit 1pc in March – the highest since the pandemic. Businesses, however, can’t pass these costs on to customers, largely because they are not spending.

Retail sales rose an annually sluggish 1.7pc in March, and in April car sales dropped by more than 25pc. The household savings rate was 37.8pc in the first quarter, the highest recorded (with the exception of the pandemic).

Consequently, if the situation continues to escalate and oil prices keep rising, then there is going to be some damage.

Exports to the rescue?

China’s get-out-of-jail card is its exports. The country’s use of coal, wind, and solar has insulated its producers from the global energy shock, helping to keep export prices competitive.

Export growth slowed to 2.5pc year-on-year in March, but a key indicator of activity at export-oriented firms in April hit 52.2, its highest level in more than five years.

That buoyancy in part reflects Chinese factories’ dominance of the supply chain for wind turbines, solar panels, batteries, and electric cars. The soaring oil price has brought green tech back into worldwide fashion.

Exports of solar cells doubled in March, and were up by more than a third for lithium-ion batteries.

Nonetheless, this tech, together with electric vehicles known in Beijing as “the new three”, still comprises just 7pc of China’s exports. The wider trading picture will be more worrying for China.

If the Strait of Hormuz remains closed for several more months, the blow to the global economy will get exponentially bigger – and the appetite to buy goods from China may wane. Exports to the Middle East are already suffering. On Zhihu, one post related how a toy exporter had seen a 20pc to 40pc drop in demand. “Even Saudi Arabia and the UAE are waiting and watching, afraid of escalating conflicts. No one dares to act recklessly.”

The real pain could come from south-east Asia. It has been a crucial shock absorber for Chinese exporters who have had to drop out of the US market since Trump returned to the White House. But many of these countries are Hormuz-dependent, and the war has hit them hard.

If its trading partners don’t want to buy so much, then China won’t be selling so much either.

This is the tripwire that could set off China’s first time-bomb. Beijing has spent decades subsidising its industries to produce more and more, but China’s massive domestic consumer base simply refuses to spend.

This means the only place for factories’ over-production is the world market. But, if demand for exports falters, the cracks in the Communist Party’s model will open wider and wider.

The trouble is, the only way out of this impasse could be a worldwide trade war.

A broken economic model

China’s most well-known company, these days, is probably the electric car giant BYD. In just two decades, it has risen to the pinnacle of the global EV market. Yet, all is not well. Its first-quarter profit is down 55pc, to a three-year low. Its inventory of unsold stock has stacked up by 16pc since the start of the year.

BYD and fellow carmakers are capable of producing more than twice the number of vehicles each year that they can actually sell within China.

At home, this forces BYD and its rivals into a price war, squeezing margins. Domestic sales, though, have still declined for seven straight months.

Meanwhile, exports are booming. BYD’s overseas sales jumped more than 50pc in the first quarter, accounting for 45pc of all sales.

Its market share in Europe might still be only 2.2pc, but aggressive discounting in Germany has helped more than double this figure in the past 12 months.

BYD’s story is a microcosm of the successes, failures, and risks of China’s economic model.

The system builds powerful companies, but relies on the rest of the world to pick up the tab.

China’s trade surplus with the rest of the world hit $1tn last year. This is, in effect, a monetary gauge of the de-industrialisation of the West, and the stymieing of industrial development in poorer countries.

The rest of the world’s tolerance for this is gradually waning. Trump may have stepped back from his tariff war, but many observers suggest it’s only a matter of time before China provokes a wider backlash.

China’s strategy is always outbound, export driven, because they don’t have the demand. So, it’s not going to change. But of course, individual countries could change, the world could change.

The reckoning is already approaching. Countries are realising that they need some economic security. That means maybe not getting the absolute rock bottom price but having to pay something in order to have diversified suppliers.

The only way Beijing can head off the consequences of an export downturn would be to bolster demand at home. However, this is now a deeply entrenched problem.

China’s consumer confidence index stood at 92 points in February. That was a three-year high, but before the property crash the index was never below 100. It appears that the Chinese do not want to buy consumer durables; they buy consumer staples, cheap goods that are consumed every day.

Households face insecurity on every front. Their real incomes grew 4pc in the first quarter, but have been slowing for years from the 6pc-plus rate pre-Covid.

House prices, which plunged after the authorities called time on a property bubble in 2021, are still falling everywhere except Beijing, Shanghai, and a handful of other large cities.

Property is still the biggest asset held by Chinese households. If housing continues shrinking in value, that just works against the authorities’ other efforts to try and stimulate consumption.

The jobs market is also failing to inspire confidence. The unemployment rate of 5.4pc is at a three-year high. The youth jobless rate has been improving, but is still high at 17pc.

Graduates of elite universities are still finding jobs, and some businesses are still hiring, however life is tough for young people further down the ladder.

The government has tried to stimulate consumption, but in a piecemeal fashion. Its signature effort last year was a trade-in scheme for white goods, which delivered at best a mild and temporary boost.

Many hoped that a recent meeting of the Communist Party’s Politburo would recognise that the economic model was unsustainable. Disappointment followed.

There were no concrete measures or targets around anything that would boost household consumption, say analysts at Capital Economics.

Without targets for lower tiers of government, they say, nothing will change.

“A lot of the high-level policies are focused on boosting domestic self-sufficiency, on AI and tech development… It feels like those will continue to be the priorities. That might come at the cost of, or instead of, boosting support for households.”

Beijing has apparently decided that its export-oriented model won’t trigger a trade war, or hobble the profits of its companies.

Some say the regime may see more risk in changing course than in sticking to what it knows, and projecting stability. However, sitting on their hands represents the real risk.

As soon as Western countries start threatening demand, China will be severely hampered. It will mean factory closures. It will mean spiralling deflation, on top of the deflation we’re already seeing because of overcapacity and over investment. This will become catastrophic for the average Chinese household.

Two more time-bombs: No babies, no budget

The deep-seated consumer anxiety may be one reason why many Chinese are choosing not to have children.

A recent Rhodium report noted that the 7.9 million births last year was half the number a decade ago. Births are at 1939 levels – below even the time of the one-child policy (which ended in 2016).

As the death rate creeps up, the country will lose nearly 60m people in the next decade – a population almost the size of France.

Beijing has offered a 3,600-yuan (£390) subsidy per child for three years, starting last year. But government policy seldom reverses a demographic decline.

The population loss is going to make the problem of domestic under-consumption much, much worse.

That’s going to present a massive headwind to China’s economy, and that’s why they will be hoping to gain productivity benefits from new technology like AI, to offset that.

Rhodium says this will create a massive budget headache for Beijing, as the government is forced to support an older population with fewer taxpaying workers.

However, Beijing is already fiscally neuralgic. Government revenue is now almost static, with tax income flatlining and land sales declining.

The public debt-to-GDP ratio is about the same as Britain’s. The budget deficit was 9pc of GDP last year, and could widen further. By 2030 this would be entering crisis-level territory.

Meanwhile, the public and private lending that washes through the Chinese economy, putting China “in a league of its own”, according to Capital Economics, is “a signal that all is not well”.

Rhodium’s warning is even more stark: “The era of fiscal trade-offs has already arrived, and the stress is deepening . . . This is what fiscal and financial decay looks like.”

Searching for a prop

Beijing hopes that AI and robots will defuse these time-bombs. Tech-fuelled productivity growth could prop up the economy if China’s population is falling and the world is turning away from its export wares.

China has one big advantage. In a command-and-control economy, the Communist Party can get businesses to adopt AI, and can build out the infrastructure to support it.

The Chinese also seem to be taking to it very quickly, to a greater extent than the average consumer in the US or in Europe. AI is being directly embedded into the commercial stacks that people use on a daily basis, the e-commerce or content platforms that the Chinese use.

The government is also on board. Technology isn’t just an economic panacea; it’s a must-have in Beijing’s relentless quest for self-reliance.

Just days ago, Ding Xuexiang, the vice-premier, said: “China’s AI must take the path of independent innovation, to have the confidence to withstand any containment or suppression”.

And yet, the Communist Party may also be its own worst enemy. Beijing’s refusal to rely on America for chips – instead pushing companies to use domestic Huawei alternatives – is holding back development.

Officials will also be fretting that AI might destroy more jobs than it creates – an outcome the regime wouldn’t be able to stomach.

What you might see is a lot of companies adopting AI, seeing productivity improve, but then not being able to follow through with the kind of lay offs that would result from that in most other economies. And, then, you don’t actually see a boost to labour productivity.

Beijing also has a broader insecurity about technology: it must rely for innovation on the private sector, which the leadership simply doesn’t trust.

The feeling is mutual. Xi’s 2020 attack on Jack Ma, founder of the fintech firm Ant, left lasting scars on China’s entrepreneurial class.

Such fears have been renewed with Beijing kyboshed Facebook owner Meta’s proposed merger with Singapore-based AI firm Manus. Manus’s Chinese founders had moved the company to Singapore, but not beyond the reach of the Communist regime. Some say that if you’re a private entrepreneur in China, what incentives do you have in trying to go global, if this can always happen, and the Party can just come in and say, ‘All of your work, it’s ours now’?

Other analysts are of the opinion that the Xi regime’s innate fear of losing control will be its undoing, and hobble its tech push. The signature feature of Xi Jinping and his administration is how conservative it is. It is not a radical, progressive, transformative regime. In the back of their mind, they’re always thinking, ‘We can’t change too fast’.

China has built a robot that can win a marathon. The question, though, is whether it can build an economic model that can keep the country competitive.

Trump’s war in Iran, if it lasts well into the year, may force out an answer.

Standard